Home Insurance in Madison and Huntsville: Why Alabama's Storm Season Makes Coverage Critical
Spring in Madison and Huntsville brings longer days, warmer temperatures, and the return of Alabama's severe weather season. North Alabama sits in the heart of Dixie Alley — a regi...
Madison and Huntsville · Community Photo
Spring in Madison and Huntsville brings longer days, warmer temperatures, and the return of Alabama's severe weather season. North Alabama sits in the heart of Dixie Alley — a region that experiences some of the highest tornado activity in the country — and the spring months from March through May are statistically the most active period for severe storms in the state.
For homeowners in Madison and the greater Huntsville area, that seasonal reality makes home insurance not just a mortgage requirement but a genuine financial necessity worth understanding properly.
What Alabama Homeowners Are Actually Exposed To
Alabama's severe weather profile is unusually broad. Tornadoes, straight-line winds, large hail, flash flooding, and lightning strikes all represent real and recurring risks for homeowners in the Tennessee Valley region.
A standard homeowner's policy covers the dwelling itself, personal property, liability, and additional living expenses if the home becomes uninhabitable — but the details of what is and is not covered, at what limits, and subject to what deductibles vary enormously between policies. Many homeowners discover these gaps for the first time when a claim is filed after a storm, which is the worst possible moment to learn about them.
Key Coverage Questions to Ask
There are several areas where homeowner policies in Alabama frequently leave gaps worth reviewing with a local agent:
- Dwelling replacement cost vs. actual cash value — replacement cost coverage pays to rebuild at current construction costs; actual cash value coverage factors in depreciation and often falls short of what rebuilding actually costs today
- Wind and hail deductibles — some policies carry a separate, higher deductible specifically for wind and hail damage, which can be a percentage of the dwelling's insured value rather than a flat dollar amount
- Flood coverage — standard homeowner's policies do not cover flood damage; for properties in low-lying areas of Madison County, a separate flood policy through the National Flood Insurance Program may be worth considering
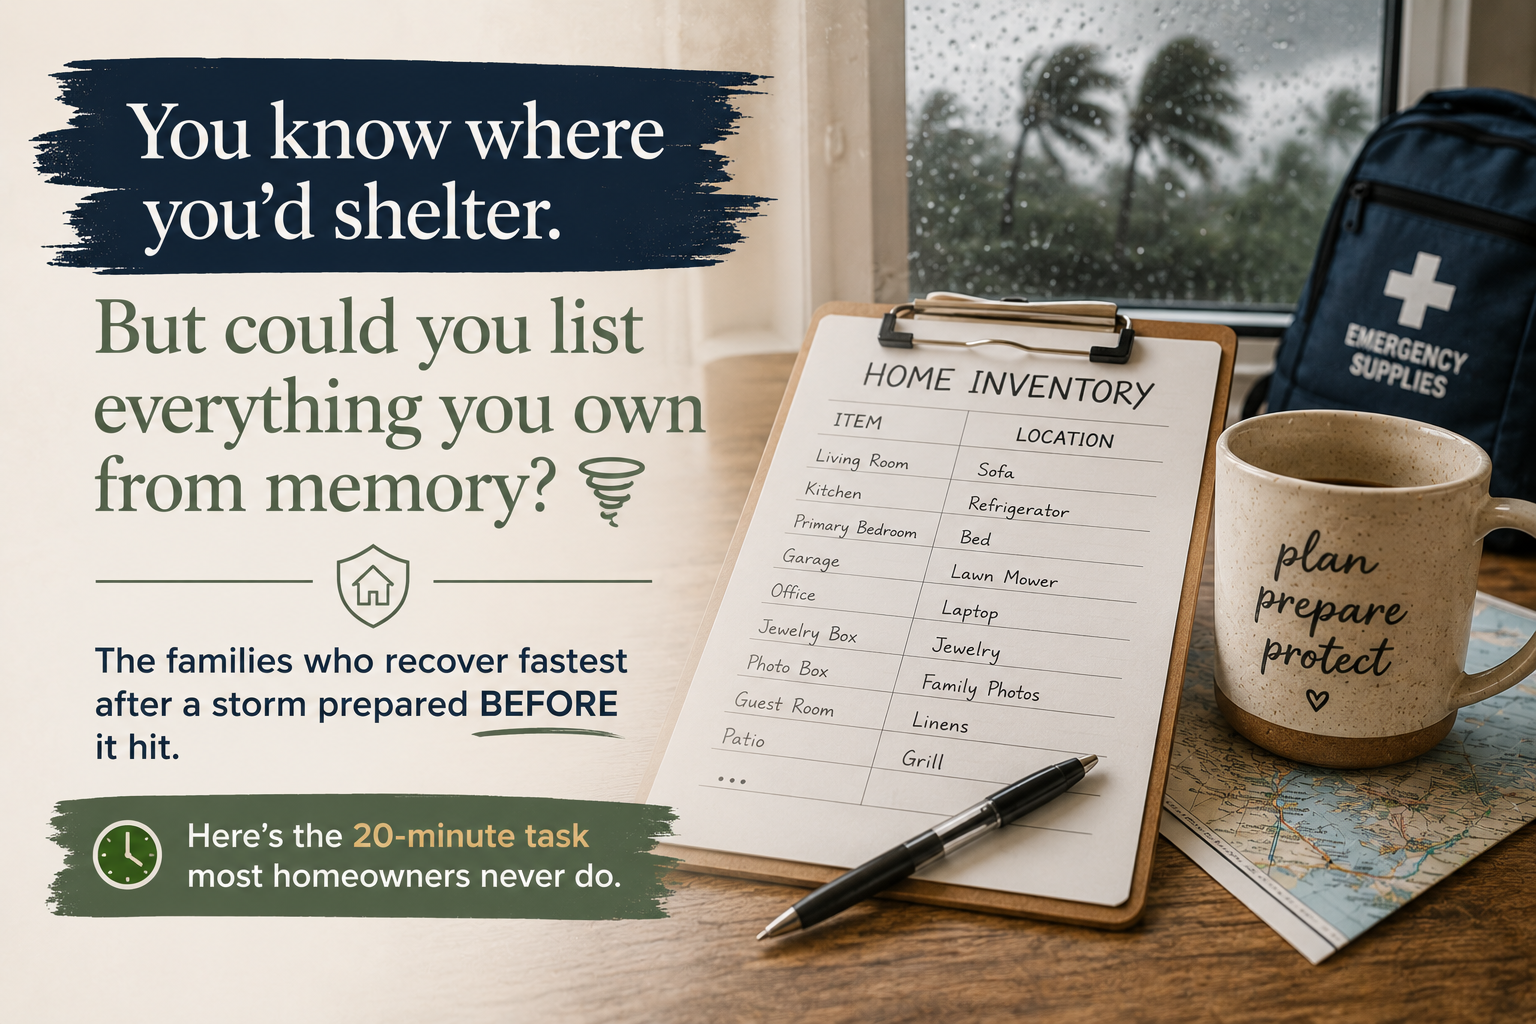
- Personal property limits — high-value items like jewelry, electronics, firearms, and musical instruments often have sub-limits under standard policies and may need a separate scheduled endorsement
- Loss of use coverage — if a storm makes the home temporarily uninhabitable, this pays for additional living expenses; the limits and duration of this coverage vary significantly
The Case for an Annual Policy Review
Home values in Madison and the Huntsville metro have risen considerably in recent years. A policy that was adequate three years ago may significantly underinsure the same home today, leaving the homeowner short of what it actually costs to rebuild. An annual review with a local agent who understands the current construction and material costs in North Alabama is one of the most practical financial maintenance steps a homeowner can take — and it costs nothing to have the conversation.
Talk to Kevin Baggett at Alfa Insurance
Don't wait for storm season to find out whether your coverage is adequate. Kevin Baggett at Alfa Insurance is ready to review your current policy and identify any gaps before they become an issue.
- Website: alfainsurance.com/agents/kevin-baggett
- Email: kbaggett@alfains.com
- Phone: (256) 258-5051
Source: alfainsurance.com
Header Image Source: Scott Osborn on Unsplash